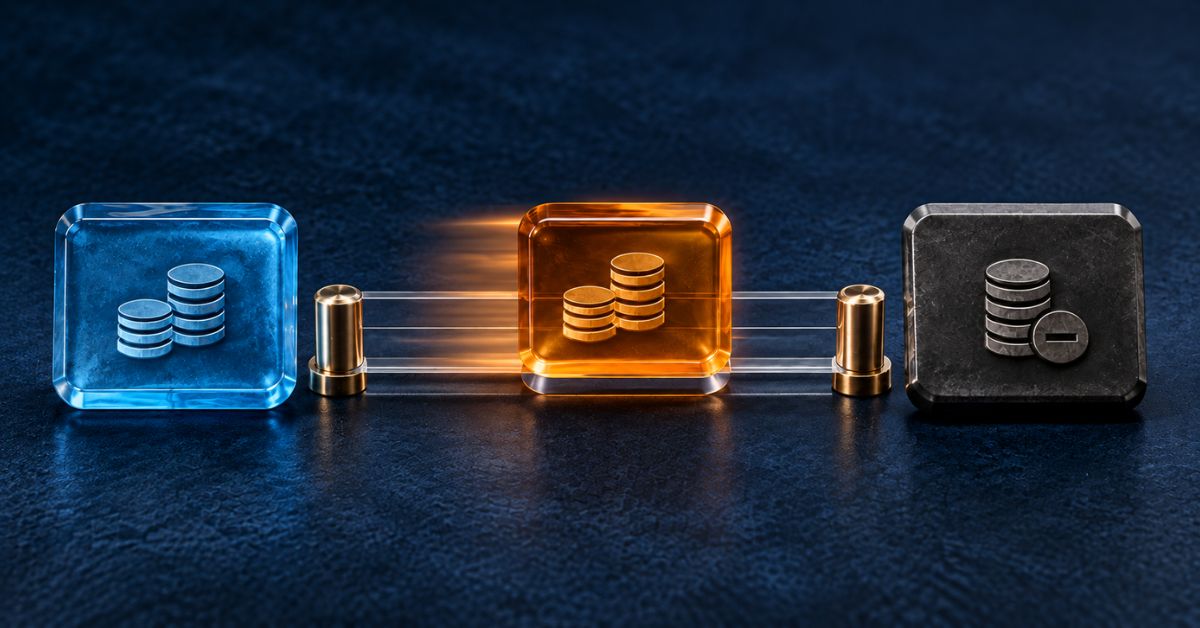
A healthy bank balance can be wonderfully reassuring. It sits there on the screen looking confident, available, and ready to tackle the week.
Then payroll is due. A large supplier payment is waiting. Three customer refunds are still processing. A card settlement has not landed yet. Suddenly, that cheerful number is not telling the whole story. The issue is not that the bank balance is wrong. It is simply incomplete.
For a growing business, cash does not move in one tidy, predictable line. It travels through payment rails, approval stages, settlement windows, currency conversions, reserve arrangements, and the occasional compliance review that appears at precisely the least convenient moment.
That is why a business can look cash-rich on paper and still feel cash-tight in real life.
The Difference Between Cash You See and Cash You Can Use
Your bank balance shows what has reached the account. Your cash position should show what is genuinely available after taking account of commitments and money still moving.
That may include:
- Incoming customer payments that have been initiated but not settled
- Outgoing supplier payments that are approved but have not yet left the account
- Card settlements expected over the next few days
- Refunds that have been issued but not completed
- Funds held in a reserve or temporarily unavailable
- Payroll, tax, or loan payments due soon
- Foreign-currency payments whose final value may change before settlement
This is where finance teams can get tripped up. A balance may include money that is technically present but already spoken for. At the same time, it may exclude revenue that is expected soon but cannot safely be used today. In other words, the balance is a photograph. Your real cash position is the movie.
Why Funds in Transit Create Bad Decisions
Imagine a business sees a comfortable balance on Monday morning and approves an additional supplier order. What it has not fully accounted for is a large batch payment scheduled for later that day, customer refunds due to be processed, and card settlements that will not arrive until Wednesday.
Nothing has gone wrong. Yet the timing has.
This can lead to rushed transfers, delayed supplier relationships, missed payment deadlines, unnecessary short-term borrowing, or a finance team spending the afternoon performing spreadsheet acrobatics.
Growing businesses are especially exposed because payment volume increases faster than visibility. What worked when there were ten transactions per week becomes fragile when there are hundreds, several currencies, and multiple payment providers involved.
Using a platform such as CruisePay Finance can help businesses bring payment activity into a clearer operational view. However, even the best tools need a sensible process behind them. Visibility is only valuable when someone is using it to make better decisions.
Build a Cash Position That Looks Forward
A useful cash position should not stop at “What is in the account now?” It should ask, “What will be available after the next few days of movement?”
Start by separating money into simple categories:
Available Now: This is cash that has cleared and is not already committed to a confirmed outgoing payment.
Expected In: This includes funds that are likely to arrive, such as customer transfers, settlements, or scheduled receivables. Treat these as expected, not guaranteed, until they have cleared.
Committed Out: These are approved supplier payments, payroll, tax obligations, refunds, subscriptions, and other amounts that will leave the business soon.
Restricted or Delayed: This includes reserves, held funds, pending reviews, payment disputes, or amounts tied up in a different currency or account.
Once these categories are visible, the picture becomes far less misleading. A large balance may be less exciting than it first appeared, but it will be much more useful.
Watch the Settlement Calendar, Not Just the Statement
Timing matters as much as the amount. A finance team should know when major inflows and outflows are expected to happen, especially around payroll dates, supplier runs, weekends, public holidays, and cross-border payment cut-off times.
For example, a payment initiated on Friday may not move as quickly as a payment initiated early on a business day. A customer payment can also be delayed by incorrect references, intermediary banking checks, or payment-rail timing.
Create a short rolling cash view for the next seven, 14, and 30 days. It does not need to be a giant forecasting monument. It simply needs to show what is likely to arrive, what is definitely leaving, and where the pressure points may sit. That small habit can prevent large surprises.
Do Not Let “Expected” Become “Spendable”
This is one of the most useful rules in cash management. Expected cash is helpful. Spendable cash is safer.
A customer may say a payment is on the way. A settlement report may show an amount is due. A transfer may be marked as pending. All of that is positive, but it does not mean the funds are ready to support a new commitment.
Good finance teams plan with expected cash but make commitments based on available cash. It may sound cautious, and it is. Caution is quite underrated when salaries and supplier relationships are involved.
Final Thoughts
Your bank balance matters, but it should never be the only number steering your business decisions.
The healthiest companies look beyond the snapshot of “what’s in the account” and track what’s available now, what’s in transit, what’s committed, and what may be delayed.
When cash movement is visible and forward‑looking, finance teams stop reacting to surprises and start planning with confidence. In the world of business payments, money isn’t truly yours until it actually arrives.
#CashFlowManagement #BusinessPayments #WorkingCapital #PaymentOperations #FinanceTeams #CruisePayFinance #CashVisibility
Recent Comments